Your US client says, "We pay all contractors by ACH. Just send your routing number." You check your bank app. There's an account number and an IBAN, but no routing number. That's the moment most freelancers find out you can't receive ACH payments in Pakistan the same way you receive a local transfer.
You can still get paid by ACH from Pakistan. You need US account details in your own name. This guide covers what ACH is, what a routing number does, when a wire makes more sense, and why your client won't find an IBAN on US details. Everything below was checked on 26 October 2026.
Key takeaways
- ACH is the US network for everyday bank payments. It only pays into US accounts, so a Pakistani bank account can't receive it directly.
- To receive ACH, give your client a routing number, an account number, your full legal name and the account type.
- A routing number is the 9-digit code that tells a US bank where to send money. It does the job a SWIFT code does abroad.
- US accounts don't use IBANs. If a payer's form asks for one, they're on the wrong payment type.
- Most ACH payments settle within one banking day, and Same Day ACH can arrive the same day.
What is an ACH payment?
The scale explains why clients default to it. Nacha, which runs the network, says ACH carried 35.2 billion payments worth $93 trillion in 2025, including close to 8.1 billion business-to-business payments. If your client pays freelancers through payroll or accounting software, ACH is usually the default option.
ACH reaches every bank and credit union account in the US, according to Nacha. That's the catch for Pakistani freelancers: it reaches US accounts only.
Can you receive ACH payments in Pakistan?
There is a version of ACH that crosses borders, called an IAT (International ACH Transaction). Nacha defines it as the US leg of an international payment, and it can never go as Same Day ACH. The sending bank sets it up, and it isn't something you can request from your side. In practice, the freelancer route is simple: get US account details, send them to your client, and let them pay you like a local contractor.
We covered what you can and can't open from Pakistan in can you open a US bank account from Pakistan.
What is a routing number?
The American Bankers Association created routing numbers to get payments to the right bank, and about 22,000 are active today. On a US check, it's the first group of numbers along the bottom.
Here's how it compares with the codes you already know:
| Code | What it identifies | Used for |
|---|---|---|
| Routing number | A US bank (9 digits) | ACH and domestic wires inside the US |
| Account number | Your account at that bank | Every payment type |
| SWIFT code | A bank anywhere in the world | International wires |
| IBAN | A bank and account in one string | Payments in countries that use IBAN, such as Pakistan and most of Europe |
ACH or wire: which should your payer use?
| Payment type | Typical speed | Watch out for |
|---|---|---|
| ACH (client in the US) | Most settle within one banking day; Same Day ACH is faster | Name and account number typos |
| Domestic wire (client in the US) | Usually the same business day | The sender's wire fee |
| SWIFT wire (client outside the US) | Varies with the banks in between | Intermediary banks taking fees from the amount |
ACH and domestic wires need your routing number, account number and name, and ACH forms usually ask for the account type. A SWIFT wire needs your SWIFT code, account number, name and address, plus the bank's name and address.
Nacha estimates that 80% of ACH payments settle in one banking day or less. Same Day ACH, which can carry up to $1 million per payment, grew to 1.4 billion payments in 2025. Domestic wires run through the Fedwire system on business days, from 9:00 p.m. ET the evening before to 7:00 p.m. ET, with no Saturday or Sunday processing. The Fed plans to add Sundays in 2028 or 2029.
If your client is outside the US, a SWIFT wire in USD is the right route. Ask them to choose OUR charges so the full amount arrives. We wrote the exact message to send in how to receive payment from a client abroad.
Why do US account details have no IBAN?
IBAN is an international standard, ISO 13616, and Swift keeps the registry of national formats. Pakistan's banks adopted it under State Bank guidelines issued in 2012. The US doesn't: US bank SoFi puts it plainly, "The United States doesn't use International Bank Account Number (IBAN) codes."
This trips up clients in Europe and the Gulf most, because their banking apps expect an IBAN for every transfer. If they're sending from outside the US, their bank should switch to a SWIFT wire, which uses your SWIFT code and account number.
How long does an ACH payment take to arrive?
Timing depends on two things you can't see: when your client's bank submits the payment, and whether they use standard or Same Day ACH. The Federal Reserve's FedACH schedule settles payments on banking days only, so anything sent after the last window waits for the next one. If the money hasn't arrived after a few banking days, ask your client for the date it was sent and the trace number.
Which details do Upwork and clients ask for?
Upwork's help page says a new Direct to U.S. Bank method becomes active three days after you confirm it. Upwork says it doesn't charge for these transfers, and payments usually arrive in two to five business days. We're confirming Upwork payouts to HandlePay with a live payment before publishing a setup guide, so don't switch your Upwork method yet.
How to receive ACH payments with HandlePay
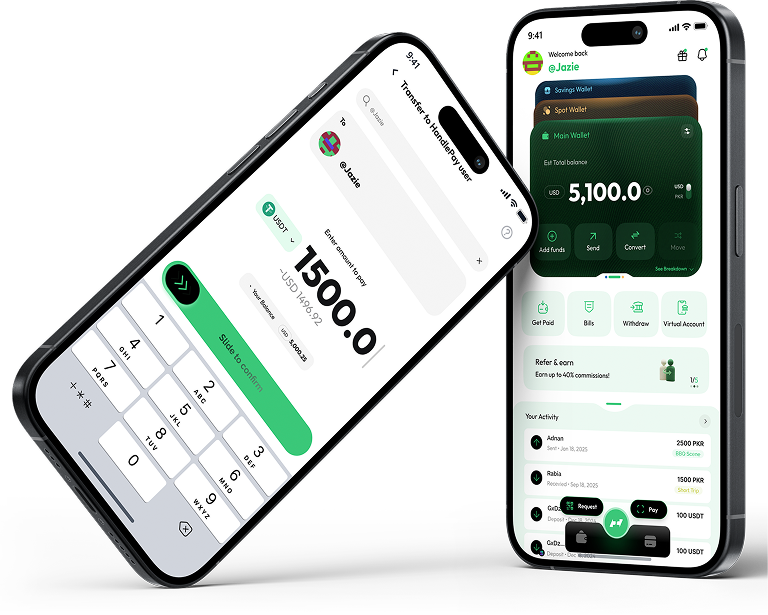
Download HandlePay and create your account with a username and a passkey
Verify your identity once
That's what puts your US account details in your own name.
Request your USD account
You get a routing number and an account number for a checking account based in the US.
Copy or share your details from the ACH/Wire tab and send them to your client
Get paid in dollars
When you want rupees, cash out to any Pakistani bank in your name. It lands within minutes, at the Google rate.
Only you can move your money once it lands. If you're still deciding whether you need US details at all, read the benefits of a dollar account.
Get your US account details
A routing number and account number in your own name. Your client pays by ACH, and you cash out to PKR when you choose.
Sources
- Nacha, "Same Day ACH and Business-to-Business Payments Propel ACH Network Volume Growth in 2025", 28 Jan 2026
- Nacha, "The ABCs of ACH", checked 26 Oct 2026
- Nacha, "How ACH Payments Work", checked 26 Oct 2026
- Nacha, "Same Day ACH Payment Limit to Increase to $1 Million"
- Nacha Operating Rules, "Definition of IAT Entries" (effective 18 Sep 2026)
- American Bankers Association, "ABA Routing Number", checked 26 Oct 2026
- Swift, "IBAN" (ISO 13616 registry), checked 26 Oct 2026
- SoFi, "IBAN vs SWIFT Code: Differences Explained", 11 Jun 2026
- Federal Reserve Financial Services, "Fedwire Funds Service and National Settlement Service Operating Hours", checked 26 Oct 2026
- Federal Reserve Financial Services, "Fedwire Funds Service and NSS Expansion of Operating Days", checked 26 Oct 2026
- Federal Reserve Financial Services, "FedACH Processing Schedule", checked 26 Oct 2026
- State Bank of Pakistan, PSD Circular No. 02 of 2012, IBAN Implementation Guidelines, 15 May 2012
- IRS, "About Form W-8BEN", checked 26 Oct 2026
- Chase, "What are wire transfer fees?" (intermediary bank fees), checked 26 Oct 2026
- Upwork Help, "Direct to U.S. Bank", checked 26 Oct 2026
- Upwork Help, "Direct to U.S. Bank timing and fees explained", checked 26 Oct 2026
FAQs
HandlePay Team
Our mission is to make international money work for everyday people, freelancers, and businesses in Pakistan.